
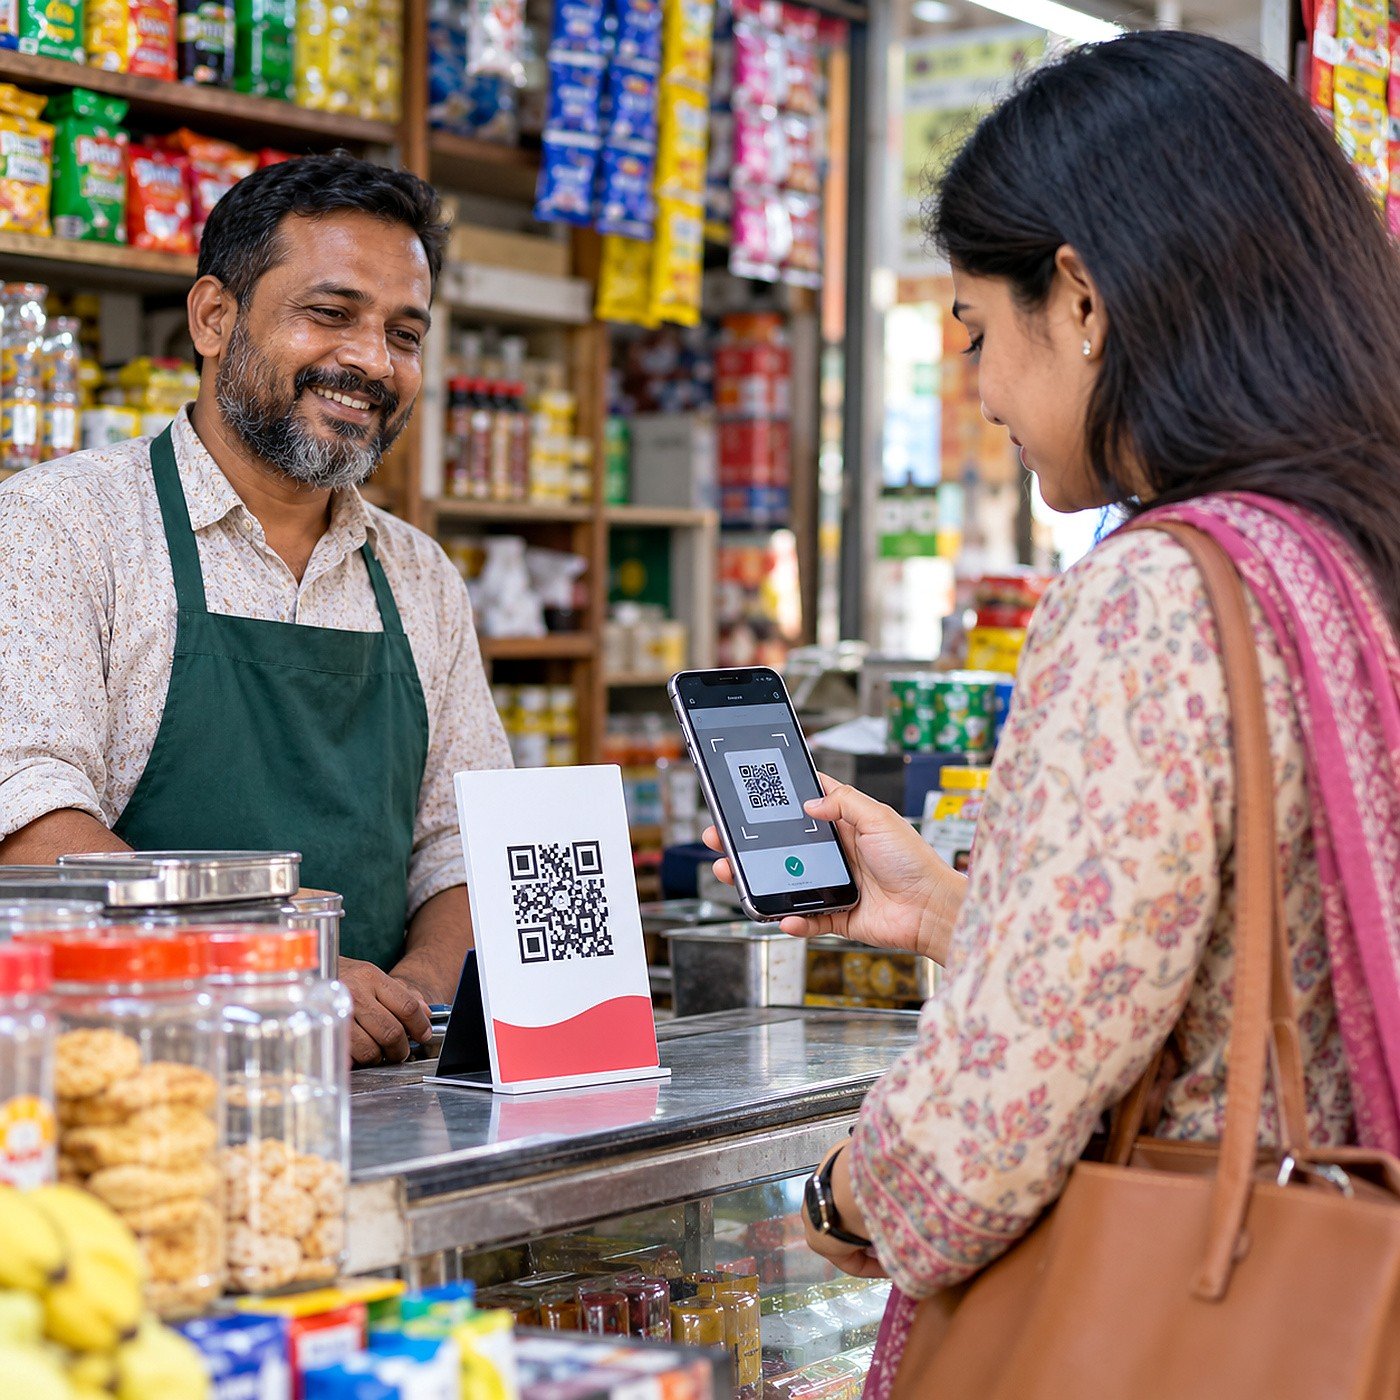
Bangladesh Bank has introduced a structured dispute-resolution framework for Bangla QR merchant payments, adding clearer protections for customers and businesses as digital transactions become more common. The guidelines set out responsibilities for customers, merchants, issuing banks, acquiring institutions, payment service providers, payment system operators and other parties involved in QR transactions. They cover common problems such as failed, reversed, duplicate or unauthorised payments and establish procedures for complaints, investigation, refunds and settlement. One of the most useful features is the introduction of defined timelines, including automatic reversal of failed transactions and procedures for merchant-initiated refunds. Clear timelines matter because uncertainty after a failed digital payment can reduce trust quickly. A customer may worry that money has been deducted without reaching the merchant, while a merchant may be unsure whether to provide goods or wait for confirmation. A formal process helps both sides understand what should happen next and which institution is responsible. Banks and payment providers are also required to preserve transaction records and supply information needed for investigations. Disputes routed through the National Payment Switch Bangladesh are covered by the framework as well, creating a more consistent system across participating institutions. The new rules come as Bangla QR is being promoted as a convenient national payment standard that can work across different banking and financial-service apps. For small merchants, QR payments can be attractive because they require less hardware than traditional card terminals. For customers, a single interoperable QR system can make digital payment easier in shops, restaurants and service businesses. However, adoption depends on confidence that errors will be corrected quickly. Strong dispute handling is therefore part of the payment infrastructure, not simply an administrative detail. The guidelines also require proper communication with customers during the resolution process, which can reduce confusion and improve service quality. Bangladesh’s digital-finance sector is growing rapidly, and payment systems will need increasingly professional consumer-protection standards as transaction volumes rise. If banks, MFS providers and payment operators apply the framework consistently, the new rules can make Bangla QR safer and more dependable. Better protection can encourage more consumers to pay digitally and give merchants greater confidence in accepting QR transactions, supporting Bangladesh’s broader move toward a more efficient cashless economy.